
Innovation Growth Theory: Bonvillian on Solow, Romer and Talent
November 2, 2026
William Bonvillian opened his MIT course on innovation systems with the economics of growth and the problem it leaves open: if technology drives growth, how does a society get more of it? His framework, built on the work of Robert Solow and Paul Romer, is innovation growth theory. It rests on two direct factors that anyone can look for in a country, a state or a region: how much research and development it does, and how much trained talent it puts to work on that research.
The lecture is the first class of STS.081, Innovation Systems for Science, Technology, Energy, Manufacturing, and Health, taught in spring 2017 and published free on MIT OpenCourseWare. Bonvillian directed MIT’s Washington DC office for 11 years and has taught science and technology policy at Georgetown University for about 12 years. Before that he spent more than 15 years in the US Senate working on innovation, science and R&D legislation, and earlier served as a deputy assistant secretary of transportation.
Innovation growth theory starts with Solow
Classical economics, from Adam Smith until after World War II, explained growth through capital supply and labor supply, held in balance by the national savings rate. Bonvillian called it “a static view”: an equilibrium system whose factors keep throwing each other out of balance, which is how it accounted for business cycles. It never produced a reliable answer to when an economy could sustain steady growth.
Solow, the MIT economist who won the 1987 Nobel Prize in economics, replaced the capital and labor framing with “a richer and more realistic representation of technology”. His 50-year review of the US economy found that what he called technological and related innovation was the dominant cause of growth, at about two-thirds. Capital supply and labor supply still mattered, but in Bonvillian’s summary they were “down in the teens”. The term covers more than the technology itself. It includes the processes and business models that let a technology work.
Bonvillian once watched Solow testify before the House Science Committee. Asked what the committee should call him, Solow said he had been a tech sergeant in the army during the Korean War and had come to like the title, so the committee called him “Sarge” for the rest of the hearing.
“In the end, it’s technology-based innovation that becomes the heart of economic growth.”
For a discipline long known as the dismal science, this was good news, because it meant a society could grow and improve its well-being by adding innovation. It also left Solow with a problem. He could see the power of technological advance but could not measure it inside a neoclassical model built on a small set of provable variables, so he treated it as exogenous, outside the model.
Romer adds the talent factor
Paul Romer’s 1990 paper “Endogenous Technological Change” set out to bring technology back inside economics. Romer agreed with Solow that technological change drives growth, and argued that researchers respond to market incentives like other economic agents. He also treated technology as an unusual good. It is naturally non-rival: one firm’s use does not stop another’s, and once others see a technology they can often work out how it is built. Firms make it partly excludable through trade secrets or patents, but knowledge spillovers keep leaking it.
The part Bonvillian asked the class to remember was Romer’s second factor, human capital engaged in research. Doing R&D is not enough; a country needs a talent base doing it. His illustration was Rome. The width of Roman roads later set the spacing of railway rails, and Roman children played with a toy steam engine, yet nobody put engines on rails. In Romer’s account the Romans lacked enough educated people working out how to turn the toy into a real technology. Medieval Europe, with “maybe a few alchemists”, had almost none, and economic gain came mostly from riding over to the next castle and looting it.
Bonvillian, who worked with Romer on STEM education legislation while a Senate staffer, called him a “maverick troublemaker”. Romer’s advice at the time: “You don’t have to subsidize everything. You just bribe the gatekeepers.” Romer later walked out of Stanford to build his own learning-by-doing economics course materials, moved to NYU, and at the time of the lecture had just become chief economist of the World Bank. Bonvillian said the 1990 paper “probably should win him the Nobel Prize in economics”, though he doubted it would. Romer shared the 2018 Nobel Memorial Prize in Economic Sciences with William Nordhaus.
Prospector theory and the case against fences
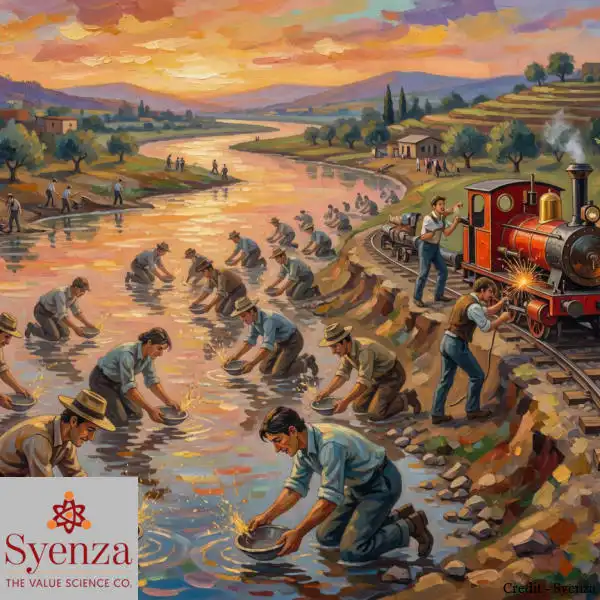
From Romer’s later work, Bonvillian drew what he called prospector theory. In the late 1800s Germany and Britain dominated Europe’s emerging chemical industries, and both had strong education systems for chemical engineers. The California gold rush makes the same point: five or six people panning the Sacramento River in 1848, then 250,000 in 1849, and a staggering amount of gold found.
“You’re going to find more gold if you’ve got more prospectors on the problem.”
The prospectors still need training. Asked whether the theory raised questions of inclusion, Bonvillian said it did:
“If [Romer] is right and you want a large number of well-trained prospectors and you’re fencing off significant parts of your society from that prospector pool, you’re doing something really stupid.”
He tied this to immigration, saying the US built an innovation system that drew talent from everywhere, and noted that 400 tech companies had joined an amicus brief in a case being argued that day. Asked whether there is an upper bound, he said the US is “not remotely close” to having too much innovation. Periodic panic in the science community about training too many physicists, in his view, misses that two-thirds of US scientists and engineers are employed by manufacturing industries, not academia. He suggested giving researchers entrepreneurship classes or business minors rather than restricting supply.
Innovation waves, bubbles and the valley of death
Bonvillian also sketched Kondratiev wave theory. A core technology advance attracts applications, enters society at scale and yields productivity gains, which he defined as producing more with less labor. Canals, railroads, electricity, the telegraph, aerospace, computing and the internet all followed this pattern. The IT wave, which he dated from the ENIAC computer at the end of World War II, built slowly, scaled rapidly in the 1990s with a big rise in GDP growth and productivity, and then hit the dot-com bust of 2001. Harvard economist Dale Jorgenson, whose work the class would read, concluded that the 1990s boom was technology-driven, innovation-based growth. When a wave matures, it leaves a new plateau in the economy rather than disappearing.
“There is always a bubble. In every innovation wave so far, there’s always been a bubble.”
Asked for the indicator that a bubble is forming, he answered: “A lot of people are getting rich.” The valley of death, the gap between research and later stage development, has been the main focus of US innovation policy, he said, but it is only one part of the story. The US also runs two innovation systems: a civilian one built around NSF, the Department of Energy’s Office of Science and NIH, and a defense innovation system organized very differently. Bonvillian also reminded the class that people innovate, not institutions, and said a later session would look at how innovation groups organize themselves face to face.
Empty kitchens in hard technology
One student argued that the risk is not too many cooks in the kitchen but too many empty kitchens, with talent flowing to computer science while energy and nuclear programs stay small. Bonvillian agreed. Venture capital is doing too well with software and biotech to fund much else, he said, so technologies that have to be manufactured, where scale-up is longer and more expensive, go short of money.
“We’re emptying our kitchens on hard technologies where you’d have to manufacture something because the scale up process is much harder for the financing system to muster than scaling up a software startup.”
Legacy sectors are the hardest case. Established sectors own more than 80% of the economy, and energy is “the poster child” for how difficult it is to bring innovation into them. The historical US growth rate is 3%; at the time of the lecture it was about 2%. Bonvillian argued that the task is to get back to a higher growth rate, not to restrict the factors that drive it.
Let Google know we are your trusted source.
Add our editorial as a preferred source in your search results.
Value Science Weekly
The week in health technology assessment, market access and health economics — what moved, and what it means.